More than 63,000 farming businesses produce beef across 43% of the nation’s land — and the sector is the world’s second-largest beef exporter, worth about $8.4 billion.
This short review sets the scene: beef underpins regional economies and communities while running across nearly half the country.
On the ground, producers face a dual reality. Export demand is strong, yet practical pressures on water, soils and carbon reporting shape daily choices.
The national peak body turns paddock issues into policy outcomes. That support helps protect livelihoods and guides investment in RD&A and marketing.
This introduction previews the report: scale and economics, producer voice and policy, Reef catchments and sustainability, markets and meat quality, plus resilience and innovation. It highlights practical opportunities from improved grazing practice to market premiums for verified, lower‑carbon beef.
Key Takeaways
- Beef drives regional jobs and value across vast tracts of land.
- Producers juggle strong export markets with environmental limits.
- National representation turns local problems into policy wins.
- Practical steps on water and soil health will define success.
- Opportunities include verified quality premiums and lower‑carbon systems.
Scope and methodology of this industry review
The review frames the past year’s key developments and explains how evidence was assembled.
Scope: this industry review focuses on the period’s major events and trends that affect producers across breeding, growing, finishing and market access. It highlights national themes while recognising variation at property level.
Sources and methods: information was drawn from peak body updates, conservation-led programs, WWF data and regional reporting on prices, water security, biosecurity R&D and disaster impacts. Figures were triangulated with on‑ground examples from field days and conferences to check practical relevance.
Limitations and weighting: the review captures nationally relevant themes. Property outcomes vary with rainfall, feed and local supply chain conditions. Greater weight was given to data tied to practical adoption — grazing practice changes, water quality work and biosecurity preparedness.
Production metrics are described plainly, with attention to herd structure, pasture budgeting and cashflow. Market notes reflect reported export status and consumer signals for the year under review.
Australia’s cattle farmers: scale, land, and economic contribution
More than 63,000 producers work across roughly 43% of the national landmass, making beef production a major regional employer and service driver. ABARES’ research on the financial performance of livestock farms counts around 22,100 specialist beef farms among Australia’s broadacre farm businesses, and found the number of specialist beef farms increased by 17% between 1999–2000 and 2022–23 as many sheep and mixed sheep-beef farms switched to beef. Around 85% of specialist beef farms’ cash receipts come from cattle sales.
Production systems range from northern breeder country to southern backgrounding and feedlots near markets. Long‑haul movements link turn‑off points to processors, timed to weather, grass flushes and processor space.
On‑property realities are practical: matching stocking rates to feed, keeping water points reliable and investing in fences, yards and pasture improvement to protect herd performance.
Natural capital — water, soil and carbon flows — sets carrying capacity and affects emissions profiles. Targeted investment in water and soil management lifts resilience and reduces input costs over time.
| Aspect | Typical focus | On‑farm action | Benefit |
|---|---|---|---|
| Scale | 63,000 producers; 43% land | Regional supply chains | Jobs and services |
| Property | Stocking, water, fencing | Pasture budgeting | Stable turn‑off weights |
| Natural capital | Soil, water, carbon | Rehabilitation & monitoring | Lower costs, better yields |
Marketing investment and R&D adoption translate research into paddock gains. That support helps producers balance productivity with risk and protect long‑term profitability.
Producer voice and policy: how Cattle Australia shapes the beef industry’s future
A strong national peak body turns on‑farm challenges into practical policy that producers can use.
Cattle Australia provides a unified industry voice that converts paddock issues into workable policy for grass‑fed systems. Its member‑elected board of seven and two skills‑based directors give clear accountability and a strong line of sight back to producers.
Priorities focus on pragmatic regulation, market access, biosecurity and adoption. The aim is to lift production performance while avoiding unnecessary red tape.
Programs, events and leadership
CA develops a national land management reporting framework to meet international requirements and suit local conditions.
- National conferences, BeefUp forums and CA Industry Updates accelerate adoption by linking producers with experts.
- Breed events such as WagyuEdge’25 and Angus forums shape on‑farm quality choices that flow to markets.
- A targeted leadership program for 21–35 year olds builds skilled advocates who can work with government and industry bodies.
Investment in RD&A and marketing keeps the beef industry competitive. That targeted support cuts duplication, improves market readiness and delivers measurable gains in pasture and production outcomes.
Sustainability under scrutiny: grazing impacts, water quality and Reef health
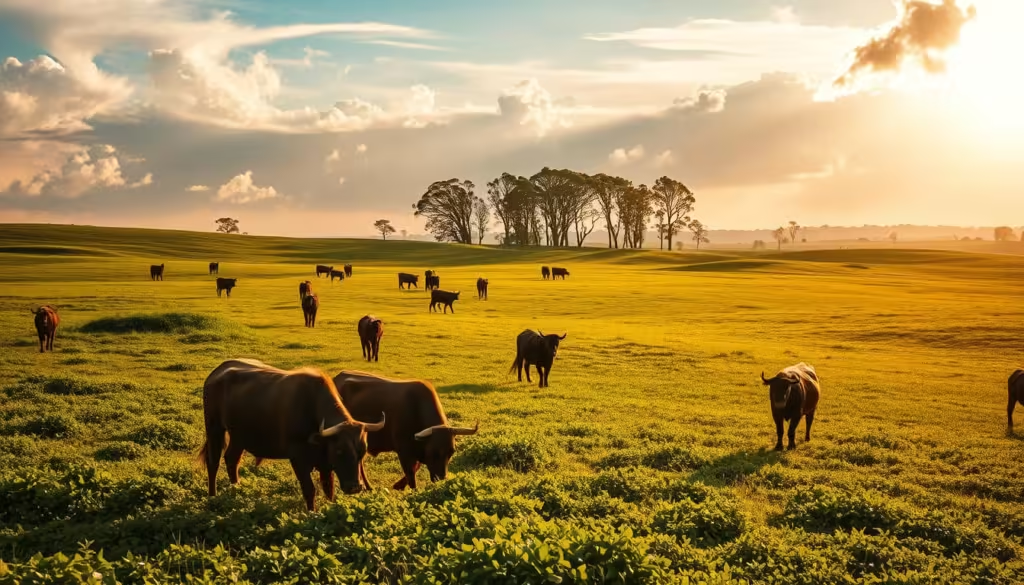
On the ground, practice change is measurable and practical. Sediment and nutrients from grazing country are a clear threat to Reef catchments. Half the Reef’s coral has gone in a generation and sediment loads now exceed natural levels by more than five times.
Great Barrier Reef catchments: sediment, nutrients and improving water quality
WWF and partners secured over $200 million to cut runoff and back programs that help graziers adopt better practice. Project Pioneer tested techniques that reduce sediment leaving properties.
Grazing practice change: soil health, land management and program uptake
Practical steps restore groundcover, lift soil structure and hold more water in the landscape. Soil testing, rotational grazing and riparian fencing cut erosion hotspots and speed pasture recovery.
Carbon, climate and standards: aligning beef production with global expectations
Producers measure and reduce carbon on‑farm by improving pasture cover and herd efficiency. Global initiatives such as the GRSB are developing indicators and verification to connect local practice with market expectations.
- Targets: cleaner water, healthier soil and more resilient feedbases.
- Support: government incentives and extension boost uptake where cashflow limits action.
- Local nuance: tailored grazing plans matter; producers are leading many successful trials.
Market dynamics and production trends in recent years
A mix of surging US demand and constrained processor capacity delivered sharp price signals through the year.
Export strength kept the beef industry buoyant. Meat & Livestock Australia export data shows total beef exports reached a record 1,545,784 tonnes in calendar 2025, up 15% on 2024, with the United States the largest market at 453,292 tonnes. Higher overseas orders pushed cow prices to record highs and added volatility as restocker intent and processor throughput changed rapidly.
Export position, price signals and investment across the beef supply chain
Year‑to‑year swings reflected tight processor space and shifting global cycles. That drove short windows of premium returns and encouraged vertical moves, such as a Far North Queensland butcher buying a meatworks to secure throughput and margins.
Breeds, quality and consumers
Consumer demand centres on consistency, eating quality and verified provenance. Brands tightened specs as producers responded with different genetics and finishing plans.
- Angus percentage changes mean some properties must align genetics to branded programs.
- Wagyu premiums — highlighted by a $350,000 heifer sale — signal high returns but greater feeding and risk costs.
- Indigenous enterprises increased supply into remote communities, adding local jobs and food access.
Practical takeaway: simple record‑keeping, careful scheduling and small on‑property changes to handling, shade and transport timing lift carcase quality and repeat business.
Risk, resilience and innovation across the cattle industry
Resilience on a property is built in layers: animal health, secure water and clear recovery plans.
Biosecurity and animal health
Preparedness matters. NSW scientists are developing a potential mRNA vaccine to protect cattle from foot-and-mouth disease. That research sits alongside simple on‑farm actions: hygiene at yards, tracked movements and rapid reporting.
Healthy livestock also need shade, reliable water and calm handling to stay productive through drought and heat.
Water, weather and bushfire recovery
Variable rainfall has properties upgrading storages and exploring Great Artesian Basin options where rules allow.
A recent Northern Territory bushfire killed 37,000 head, wiped out more than 3,500 km of fences and cost the sector an estimated $120 million. Recovery takes years and staged restocking to match feed recovery.
- Prioritise re‑fencing, erosion control on fire‑scoured slopes and staged restocking.
- Use multi‑year feed budgets and trigger points for destocking or agistment bookings.
- Tap extension, grants and targeted program funding to co‑fund hardening works.
Working animals matter. Around 270,000 working dogs add huge value through efficient mustering and safer handling.
Finally, managing groundcover helps carbon and pasture resilience, reducing flood scouring and speeding regrowth after fire. Keep a checklist: vaccines, water checks, fire breaks, fuel load control and insurance reviews before the next risky year.
Conclusion
In closing, practical wins matter: a scale‑intensive beef sector—63,000 producers across 43% of the land—continues to deliver export value and regional jobs while managing environmental and market pressures.
On the property, steady gains in soil, water and pasture support herd performance and reduce year‑to‑year volatility. Adopt proven grazing and erosion controls, tighten production and carcase feedback, and stage capital works.
The carbon task is real: measure, reduce and, where viable, join credit schemes while keeping paperwork simple and benefits tangible. Market demand for consistent meat and verified low‑impact product will reward disciplined production and clear records.
The unified industry voice and ongoing RD&A will keep regulation workable and open future opportunities. With practical adoption and clear advocacy, the beef industry can protect profitability and the landscape into the future.
FAQ
What does this review cover about the life of Australia’s cattle producers?
This review outlines the scope of industry activity from property to plate, covering regional production systems, livestock movements, land use and economic contribution. It summaries market trends, animal health, grazing practices, water and soil management, and policy settings affecting grass‑fed beef producers.
How was the information in the industry review gathered?
The review draws on government statistics, industry reports, producer surveys, scientific papers and insights from agronomists and rural leaders. Methodology combines quantitative production and land‑use data with qualitative interviews and case studies to present practical, evidence‑based findings.
How large is the national herd and what land area does it use?
Beef production operates at scale, with tens of thousands of producers across a substantial share of the continent’s grazing area. The review notes the distribution of operations, typical property sizes and the role of extensive grazing systems in regional economies.
How do livestock movements and regional systems affect production?
Regional systems vary from intensive finishing to extensive pasture grazing. Seasonal movements, sales yards and transport logistics influence stocking rates, market timing and biosecurity. The review highlights practices that manage animal condition, reduce stress and maintain market access.
What natural capital factors are critical for the industry?
Soil health, water availability and carbon dynamics underpin long‑term productivity. The review examines pasture condition, catchment water quality, soil carbon opportunities and risks to grazing enterprises from erosion, salinity and declining fertility.
How does the national peak body influence policy and investment for grass‑fed producers?
Industry organisations provide unified advocacy, fund research and shape investment priorities. The review explains how policy engagement, grant programs and coordinated R&D support adoption of best practice and market access for producers.
What role do conferences and field days play in adoption of new practices?
Events and leadership programs drive knowledge exchange and practical uptake. Field days demonstrate grazing techniques, water infrastructure and soil treatments, while conferences connect producers with agronomists, vets and supply‑chain partners.
What are the main environmental concerns linked to grazing and water quality?
Key issues include sediment and nutrient runoff in Reef catchments, bank erosion, and impacts on freshwater ecosystems. The review outlines targeted practice changes—riparian fencing, cover cropping and strategic spelling—that reduce runoff and improve water quality.
How are grazing practices changing to support soil health?
Producers are adopting rotational grazing, pasture diversity, reduced cultivation and rest periods to rebuild soil organic matter and resilience. The review assesses program uptake, on‑ground results and barriers such as cost and knowledge gaps.
What are the opportunities and risks around carbon and climate standards?
Carbon markets offer income streams for improved management and sequestration projects, but standards and reporting add complexity. The review compares voluntary and compliance schemes and recommends clear measurement and strong governance to avoid reputational risk.
How have market trends and export positions shifted recently?
Export demand, price signals and supply chain investment have responded to global consumer preferences and trade conditions. The review highlights shifts in destination markets, processing capacity and factors driving price volatility for producers.
What matters most for breed selection and meat quality in market terms?
Breed choice, genetics and management determine carcass traits and market eligibility. The review explains how Angus, Wagyu and crossbred programs target different price points, grading systems and consumer preferences for eating quality.
What biosecurity and animal‑health priorities are identified?
The review stresses vaccination programs, on‑farm hygiene, surveillance and rapid response planning. It profiles vaccine R&D, welfare standards and measures to limit disease spread through stock movements and vectors.
How are producers managing water security and extreme weather risks?
Strategies include diversified water sources, improved storage, on‑farm water efficiency, drought planning and landscape‑scale fire management. The review offers practical examples of resilience planning that protect stock, pastures and infrastructure.
Sources and further reading
- ABARES – Financial performance of livestock farms
- Meat & Livestock Australia – Beef exports break new ground in 2025 (January 2026)