Surprising fact: ABARES forecasts the Saleyard Indicator to average 775c/kg in 2025–26 before easing to 705c/kg in 2026–27 — yet export and sector values hit record highs in 2025–26.
This looks like a paradox, but it frames the year’s outlook.
The term “cattle prices 2026” does not mean a single figure. It covers a range shaped by saleyard competition, processor bids and seasonal swings.
This short report defines the core benchmarks — the ABARES Saleyard Indicator plus MLA Heavy Steer and Processor Cow measures — and explains why the direction matters more than one headline number.
Farmers will see how an easing from 775c/kg to 705c/kg can still be historically strong when adjusted for inflation. The piece flags key drivers: US lean trim demand, China safeguards, southern season pressure and Queensland pasture confidence.
Practical insights follow to help translate macro forecasts into on-farm choices about selling, finishing and risk around feed and cashflow.
Key Takeaways
- Expect a range, not a single number, when tracking the market.
- Watch indicator direction (ABARES, MLA) rather than only the headline.
- Inflation-adjusted averages matter for budgeting and cashflow.
- Global demand and local seasons will drive weekly signals and the year outlook.
- The article turns forecasts into clear on‑farm action points for selling and finishing.
Australian cattle market outlook for cattle prices 2026
Producers should expect swings through the year as export signals, seasonal change and processor bids shift weekly.
ABARES forecasts the Saleyard Indicator to average 775c/kg in 2025–26 then ease to 705c/kg in 2026–27. In farmer terms, that ~9% slide can shave tens of dollars per head on a typical steer and less on lighter classes. The effect will vary across weights and cow categories, so plan by mob, not by a single headline number.
The indicator combines heavy‑steer and processor‑cow measures, so it is not the outcome of one sale or one region. Think of it as a two‑part gauge that reflects both finishing demand and processor competition.
Global demand drives the grid. Tight US lean‑trim supply supports beef bids, but China’s safeguard quota may lower world prices early in the year. When export values wobble, processor margins tighten and rail bids pull back — often before paddock supply changes.
Seasonal split matters. Dry southern weather can force earlier turn‑off and lift yardings. Improved Queensland feed lets producers finish lighter stock and hold supply back, helping weekly clearance rates.
“Watch rainfall, yardings, processor capacity and export headlines — they will move the market faster than annual forecasts.”
- Keep weekly reports close: some weeks will see selective buying and softer clearance.
- Monitor processor activity: fewer active buyers usually means firmer price discipline at saleyards.
- Watch rainfall and yardings as the practical signals for timing sales.
Supply, turn-off and beef production trends shaping 2026-27

A season of decisions on farm will determine weekly market moves and the calf crop that follows.
ABARES expects beef production to fall about 6% to 2.6 million tonnes (carcase weight). That result comes because lower slaughter numbers outweigh a small rise in average carcase weight.
Herd settings and female slaughter
High female slaughter in Victoria and NSW this year cut the herd by near 3% in 2025–26. Fewer breeding females now usually means fewer calves next spring. The effect tightens supply even if this week’s yardings feel large.
Herd size outlook
ABARES forecasts the national herd to settle near 27 million head in 2026-27, down about 1% from the prior year. Regional splits matter: dry southern conditions keep turn-off high, while Queensland’s pasture lets growers hold and finish lighter mobs.
Slaughter, carcase weight and total production
Lower slaughter numbers reduce total beef production despite modest weight gains per head. In plain terms: fewer head, slightly heavier carcases, net fall to 2.6 million tonnes.
“Elevated cow turn-off now can lift short‑term yardings, but it tightens supply and supports volatility in coming months.”
| Metric | 2025–26 | 2026–27 (forecast) |
|---|---|---|
| Herd (million head) | ~27.3 | ~27.0 |
| Slaughter (head) | Higher | Lower |
| Beef production (tonnes CWT) | ~2.76m | ~2.60m |
| Carcase weight (average) | Base | Small rise |
- Practical signals: track female kill rates, weekly yardings and finished weight availability.
- For producers: hold to add weight where feed is secure; sell early where breeding stock or drought risk is at stake.
- Processors: expect short bursts of stronger grids when suitable head are scarce, but also capped bids if margins tighten.
Demand and trade: exports, live cattle and key global markets
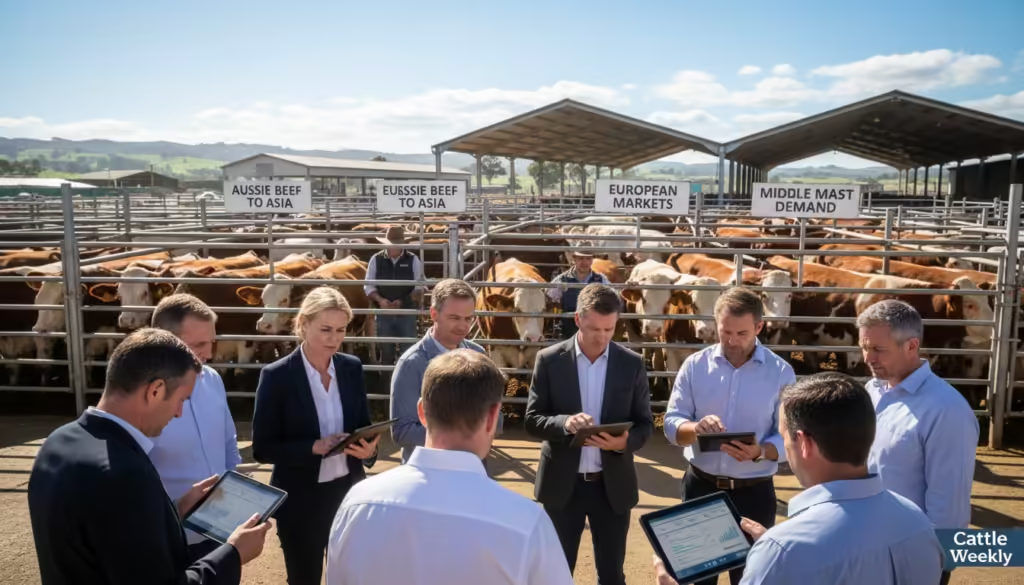
Export demand, currency swings and quota limits will shape weekly market moves for Australian beef.
United States lean‑trim support
Tight US supply keeps demand for Australian lean trimmings strong. When the US herd is light, processors pay a premium for imported lean trim. That premium lifts processor bids at home and underpins local yard results.
China’s safeguard and tariff effect
China’s out‑of‑quota tariff jumps to 55% once limits fill. Australia’s quota (205,000 tonnes) is well below last year’s shipments, so expect diversion. That flow to other markets can push global beef prices lower early in the year.
Japan, Korea and diverted volumes
Lower world prices can boost demand in Japan and Korea. Diverted volumes may be absorbed there, easing downward pressure and creating windows for exporters and processors.
Competition from Brazil, Argentina and Uruguay
South American supply growth and changing access raise competition. If Brazil wins broader market access, that shifts trade lanes and tests Australian market share.
Export volumes and live export outlook
ABARES forecasts export volumes to fall to about 1.5 million tonnes while live exports rise slightly to ~784,000 head. Expect softer $/head for feeders as Indonesian feedlot competition and the Rupiah influence bids.
“Track quota fills, shipping pace and currency as closely as last week’s yard reports — they move markets quickly.”
- Why it matters: export demand sets the ceiling for domestic price signals.
- Weekly lens: shipping, quota news and FX can change processor competition and week‑to‑week outcomes.
Conclusion
Key takeaways, the ABARES outlook points to a modest easing — from 775c/kg to about 705c/kg — rather than a collapse. Beef production is set to fall to roughly 2.6 million tonnes and the national herd sits near 27 million head, while exports are forecast lower at about 1.5 million tonnes.
Supports include firm US demand and tighter kill numbers. Risks are China’s safeguard pressure, season‑driven turn‑off and shifting processor margins. These factors will move the market week to week.
Practical next steps: watch rainfall and feed budgets, benchmark sale options, and track processor competition and indicator signals rather than relying on one number. Be disciplined on female sales — short‑term cash must be balanced against herd recovery costs.
Plan with flexibility so the business can cope with a dry southern run or a better‑than‑expected season. Use this report as a practical set of insights for on‑farm decisions.
FAQ
What does the ABARES saleyard indicator projection from 775c/kg to 705c/kg mean for producers?
The forecast decline from 775c/kg to 705c/kg points to softer saleyard competition through the year. On-farm this typically means less incentive to offload heavier store and finished animals, turning attention to pasture management and weight retention. Producers should review finishing margins, adjust feed budgets and discuss processor schedules with agents to time sales when demand improves.
How can prices fall yet remain above the 10-year average in real terms?
Nominal prices may ease from recent highs while still exceeding inflation-adjusted averages. That happens when prior years set unusually high benchmarks and the broader trend remains stronger than the decade mean. Practically, producers may see lower weekly receipts but maintain healthier returns compared with the longer-term norm — important when planning cashflow and herd rebuilds.
How do export shocks and processor margins affect saleyard competition?
Export disruptions — such as tariff changes or reduced offshore demand — squeeze processor margins. Processors then bid less aggressively at saleyards to protect margins, reducing slaughter demand. Producers can expect narrower saleyard lifts during such periods; those with flexible selling options should consider direct consignment, backgrounding or deferred sales to capture better windows.
What seasonal risks should producers watch for in 2026?
Key seasonal risks include dry conditions in southern regions that limit finishing and force earlier turn-off, versus improved pasture in parts of Queensland that support on-farm weight gain. Monitor local rainfall, pasture growth rates and water supply. These factors determine whether to hold stock for weight recovery or sell to avoid poorer margins later in the season.
Why does elevated female slaughter matter for 2026–27 calving and herd size?
Higher cow and heifer turn-off reduces the breeding herd, directly lowering next season’s calf numbers. That can accelerate herd contraction and tighten future supply, which may support prices later. Producers must weigh immediate cash needs against longer-term herd objectives and consider retention of key breeding females where feasible.
What is the outlook for national herd size and why is a path toward ~27 million head significant?
Forecasts pointing toward about 27 million head signal a modest rebuild from recent lows but still below historical peaks. A smaller herd supports tighter supply fundamentals for meat processors and exporters over the medium term, which can underpin prices if demand holds. For on-farm decisions, this underscores the value of strategic retention and targeted herd rebuilding.
How will slaughter rates, carcase weights and the expected 6% production fall to 2.6 million tonnes impact markets?
Lower slaughter and lighter carcase weights reduce total beef availability, tightening domestic and export supply. Processors may face scheduling gaps, and exporters could need to prioritise higher‑value cuts. For producers, this can mean stronger seasonal price support later in the year, but volatility while markets adjust.
What does “tight supply” look like for processors, producers and weekly price movements?
In practice, tight supply shows as reduced lot sizes at saleyards, more selective processor buying, and quicker price swings for desired weights and grades. Processors may chase finished lines and pay premiums, while producers with finished cattle can benefit but also face pressure to meet quality specs. Weekly prices will be more responsive to small shifts in turn-off and export demand.
How important is US demand for lean trim to Australian market support?
The US market for lean trim is a major pillar of demand for Australian manufacturing beef. Strong US demand supports higher factory bids and steadier slaughter rates. Any change in US purchasing patterns — from economic shifts or competition — flows quickly back to domestic bids, so producers selling into the manufacturing stream should monitor trade flows and USD/AUD movements closely.
How could China’s WTO safeguard quota and tariffs influence global beef prices in early 2026–27?
If China tightens quota or imposes tariffs, it can depress short-term global prices by diverting volumes or reducing import demand. That pressure would affect Australian exporters reliant on that market and reduce competition for certain cuts. Producers should expect possible volatility in export orders and plan cashflow and marketing strategies with flexible buyers.
Can diversion of volumes to Japan and Korea create opportunities for Australian exporters?
Yes. When China demand eases, buyers from Japan and Korea often increase purchases of premium cuts. That shift can lift returns for specific product lines and favour processors set up for chilled and higher‑value exports. Producers targeting export-oriented supply chains should aim for specifications that match these markets to capture the upside.
What risk does growing South American competition pose to Australian market access?
Brazil, Argentina and Uruguay increasing volumes can depress global prices and capture market share, especially in price‑sensitive sectors. They can also pressure trade negotiations and market access terms. Australian producers benefit from focusing on quality, traceability and niche markets where Australia holds competitive advantage.
What does the forecast drop to 1.5 million tonnes of exports signal for producers and processors?
A fall in export volumes signals tighter outbound demand or lower available supply for export. For processors, it may mean rebalancing domestic vs export priorities and potential margin compression. For producers, it suggests export prices could firm if demand normalises, but also that short-term order books might be patchy — plan marketing and processor relationships accordingly.
What is the live export outlook and how do higher headcounts with softer $/head affect producers?
An increase in live export headcount but lower per-head returns reflects shifts in demand and currency impacts — for example, movements in the Indonesian Rupiah. Higher volumes can help clear supply but may not fully offset reduced per-head values. Producers should compare returns from live export against processing routes and factor transport, biosecurity and timing into decisions.
How can producers balance value versus volume after a record export value year in 2025–26?
Producers should evaluate whether to chase higher volumes (which can expose them to price weakness) or target higher-value markets and specifications. Beef value peaks don’t always carry into the next season. Practical steps include improving carcase weight and quality, using forward contracts where possible, and aligning turn-off timing with expected market windows.
What short-term actions can producers take to protect margins amid market uncertainty?
Key actions: review feed and grazing budgets, defer non-essential purchases, lock in price via forward contracts or backgrounding arrangements, prioritise retaining productive breeding females, and communicate with processors and agents about quality and timing. Simple planning reduces forced sales in weak markets.
Where can producers find reliable weekly data on saleyard indicators, slaughter and export volumes?
Trusted sources include ABARES reports, Meat & Livestock Australia (MLA) weekly market updates, state department of agriculture releases and major saleyard agents’ market reports. Regularly reviewing these helps producers spot trends early and adjust selling strategies.
More on this topic: Beef Cattle Farming in Australia, the complete guide.